
Mortgage Broker in Converse
By Dustin Edwards, CapFi Lending
Quick move-in homes, builder incentives and VA purchases near Randolph: Converse loans compared across more than 50 wholesale lenders.
Call or text, Mon–Sat 9–7.
Converse mortgages at a glance
Converse is one of the fastest-growing cities in northeast Bexar County. The Census Bureau counted 18,198 residents in 2010 and 27,466 in 2020, and its July 2025 estimate is 32,481, up 17.2% from the 2020 base. The city also got physically bigger, from 6.98 square miles of land in 2010 to 8.46 in 2020. Much of that growth came as new subdivisions, which means Converse buyers often face a choice the resale market doesn’t offer: the builder’s financing package or an outside lender.
Converse sits close to Joint Base San Antonio–Randolph, and its population includes 3,352 veterans (ACS 2020–2024). Add a large share of first-time buyers, and you get three dominant loan conversations here: new construction, VA and first-home financing.
- Bexar County city. The Texas Comptroller lists the City of Converse as a Bexar County taxing unit.
- Fast growth. From 18,198 (2010) to an estimated 32,481 (2025).
- Mostly owners. An owner-occupied housing rate of 74.2% (ACS 2020–2024).
- Military community. 3,352 veterans (ACS 2020–2024).
- Families. 2.86 persons per household (ACS 2020–2024).
Converse facts and sources
| Fact | Figure | Source |
|---|---|---|
| City taxing unit | City of Converse (Bexar) | Texas Comptroller, Bexar County directory |
| Population, April 1, 2010 | 18,198 | U.S. Census Bureau QuickFacts |
| Population, April 1, 2020 | 27,466 | U.S. Census Bureau QuickFacts |
| Population estimate, July 1, 2025 | 32,481 | U.S. Census Bureau QuickFacts (V2025) |
| Change, 2020 base to 2025 | +17.2% | U.S. Census Bureau QuickFacts (V2025) |
| Land area, 2010 → 2020 | 6.98 → 8.46 sq. mi. | U.S. Census Bureau Gazetteer (2010, 2020) |
| Owner-occupied housing rate | 74.2% | U.S. Census Bureau QuickFacts, ACS 2020–2024 |
| Median value of owner-occupied homes | $248,400 | U.S. Census Bureau QuickFacts, ACS 2020–2024 |
| Veterans | 3,352 | U.S. Census Bureau QuickFacts, ACS 2020–2024 |
| Mean travel time to work | 26.8 minutes | U.S. Census Bureau QuickFacts, ACS 2020–2024 |
Builder financing vs. bringing your own lender
New-home sales offices in fast-growing cities like Converse often feature a preferred lender, sometimes owned by or affiliated with the builder. That’s legal, and it can be a good deal. It’s also a choice, not a requirement, and it pays to understand what’s on the table.
What an incentive usually looks like. Common offers include a credit toward closing costs, a temporary or permanent rate buydown, or upgrades, available only if you use the preferred lender. The incentive has a real dollar value; ask for it in writing.
Affiliated business disclosures. When a builder refers you to a lender it has a business relationship with, federal RESPA rules generally require a written affiliated business arrangement disclosure. It tells you about the relationship and that you’re not required to use that company.
How to compare fairly. Ask the builder’s lender for an official Loan Estimate on the same loan type, amount and lock period as an outside lender. Then compare total cost: rate, points, lender charges, credits and cash to close. Sometimes the builder’s package wins. Sometimes an outside loan, even without the incentive, costs less over the years you expect to keep it. Sometimes the builder will extend part of the incentive no matter which lender you use. You won’t know until you ask.
Quick move-in vs. to-be-built. A finished “spec” home can close on a normal timeline. A home that hasn’t been started can take months, so think about how long your rate lock needs to last and what an extension would cost.
Our builder’s lender vs. outside financing guide goes deeper.
First-time buyers in Converse
New subdivisions often attract first-time buyers, and Converse is no exception. If this is your first purchase, a few points matter more than any single rate quote.
Know your all-in payment. Principal and interest are just the start. Add property taxes, homeowners insurance, HOA dues, any special-district tax or assessment, and mortgage insurance if your down payment is small.
Down payment options. FHA, conventional low-down-payment programs and VA (for eligible borrowers) all have different requirements. Texas statewide down payment assistance programs from TDHCA and TSAHC may help if you qualify under their income and price limits.
Closing costs and credits. Builder and seller credits can cover some closing costs, but every loan program caps how much a seller can contribute. We confirm your credit fits under the cap.
Inspect the new house. A brand-new home still benefits from an independent inspection, ideally before drywall goes up and again before closing.
See our first-time home buyer guide.
Picking a lot, plan and upgrades with the loan in mind
In a new Converse subdivision, the base price is rarely the final price. Lot premiums, elevation choices and design-center upgrades add up quickly, and each dollar affects your loan in a few ways.
Upgrades raise the loan, not always the value. The appraiser values the finished home against recent sales. Some upgrades, like an extra bedroom or a larger lot, tend to show up in comparable sales. Others, like premium finishes, may not be fully reflected. If the appraisal comes in under contract, you may need to cover the gap in cash.
Upgrade deposits can be non-refundable. Builders often ask for extra earnest money when you choose structural or design upgrades. Read the contract to see what happens to that money if your financing falls through.
Think about the payment, not just the price. A few thousand dollars of upgrades adds a modest amount to the monthly payment, but it can also push you over a debt-to-income limit if you’re close. Get a quick re-check before you add a large option.
Keep your credit steady. Between contract and closing on a to-be-built home, avoid opening new credit, financing furniture or changing jobs without talking to us first. The lender will re-check before closing.
After you move in. Keep your builder warranty paperwork organized, file your homestead exemption once you’re eligible, and watch for your first notice of appraised value from the appraisal district the following spring.
Loan programs that fit Converse
Non-QM loans
- Bank statement loans for self-employed buyers, including gig and trade workers.
- ITIN mortgages for buyers who file taxes with an ITIN.
- DSCR loans for investors buying newer homes to rent near Randolph.
- WVOE loans that use a written verification of employment.
Terms vary by lender. See all non-QM options.
Agency: conventional, FHA, VA
- VA loans for eligible veterans and service members. VA loans work on new construction when the builder and home meet VA requirements; ask the builder early whether they sell to VA buyers.
- FHA loans for buyers with smaller down payments or limited credit. New-construction FHA loans have specific documentation requirements from the builder.
- Conventional loans for buyers with documented income and good credit, including low-down-payment options.
Property taxes and your payment
Appraised value. Set each year by the Bexar Appraisal District.
What’s on the bill. Bexar County, the City of Converse, your school district and other units on the parcel, plus any MUD or PID in newer neighborhoods.
The first-year surprise. On a newly built home, the first tax bill may reflect only the lot. Your lender will escrow for the finished home, and the next year’s bill will catch up. Plan for the full amount.
Homestead exemption. File once it’s your principal residence (Tax Code §11.13). School districts must exempt $140,000, plus $60,000 more for owners 65 or older or disabled.
Watch your notice. Once homesteaded, §23.23 keeps appraised value growth to 10% a year plus improvements, and §41.44 gives you until May 15, or 30 days after your notice, to protest.
How buying in Converse works
- Pre-approval. Get pre-approved before visiting model homes, so you can compare offers on equal footing.
- Pick the home and the deal. Ask for each builder incentive in writing, with and without the preferred lender.
- Contract. Review deposit, delay, appraisal and financing terms in the builder agreement.
- Inspections and appraisal. Pre-drywall and final inspections for new homes; standard inspection for resales.
- Close. Final walkthrough, signing, and then your homestead filing.
What makes CapFi different
We give Converse buyers a real outside comparison by shopping more than 50 wholesale lenders. CapFi Lending was founded in 2017, and I’ve been in the loan business since 2004 (22 years as of 2026). If the builder’s package is the better deal, I’ll tell you.
Converse mortgage FAQs
Can I use my own lender instead of the builder's lender in Converse?
Yes. You can choose your own lender. Some incentives require the preferred lender, so compare both official Loan Estimates for the same loan type and lock period, and ask whether the builder will keep any part of the incentive if you go elsewhere.
Is Converse close to Randolph for VA buyers?
Converse is in northeast Bexar County near JBSA-Randolph, and more than 3,000 veterans live in the city. Eligible borrowers can use VA loans on resale and new homes in Converse when program requirements are met.
What school district serves Converse?
Judson ISD is one of the Bexar County school taxing units on the northeast side, but district lines follow parcels, not city limits. Look up the home on the Bexar Appraisal District site and confirm the campus with the district before you sign.
How do MUD or PID assessments affect my payment?
A MUD tax or PID assessment is added to your property taxes or billed alongside them, and it raises your monthly escrow payment. Lenders include it when qualifying you. Look for the district notice the seller must provide and ask the builder about it before you sign.
Is Converse in Bexar County?
Yes. The Texas Comptroller lists the City of Converse as a Bexar County taxing unit, and property there is appraised by the Bexar Appraisal District.
Is a quick move-in home easier to finance than a to-be-built home?
Usually simpler, because the home is finished and can close on a normal timeline. A to-be-built home needs a longer plan for pre-approval updates and rate locks. Both can work; the timeline changes the strategy.
Can I buy a Converse rental home with a DSCR loan?
Yes. A DSCR loan qualifies an investment property on its expected rent rather than your personal income. Newer homes near Randolph often draw military tenants. Lenders set their own rent-to-payment ratio, down payment and reserve requirements, and some builders limit investor purchases, so check the contract before you commit.
Sources (checked Nov 5, 2026)
- Texas Comptroller, Bexar County directory (City of Converse; Judson ISD): https://comptroller.texas.gov/taxes/property-tax/county-directory/bexar.php
- U.S. Census Bureau QuickFacts, Converse city, Texas: https://www.census.gov/quickfacts/fact/table/conversecitytexas/PST045225
- U.S. Census Bureau Gazetteer Files, places: 2010 https://www2.census.gov/geo/docs/maps-data/data/gazetteer/Gaz_places_national.zip · 2020 https://www2.census.gov/geo/docs/maps-data/data/gazetteer/2020_Gazetteer/2020_gaz_place_48.txt
- Bexar Appraisal District: https://www.bcad.org/
- City of Converse: https://www.conversetx.net/
- CFPB, Loan Estimate explainer and RESPA affiliated business arrangements: https://www.consumerfinance.gov/owning-a-home/loan-estimate/
- TDHCA https://www.tdhca.texas.gov/ · TSAHC https://www.tsahc.org/
- Joint Base San Antonio: https://www.jbsa.mil/
- Texas Tax Code §§11.13, 23.23, 41.44: https://statutes.capitol.texas.gov/
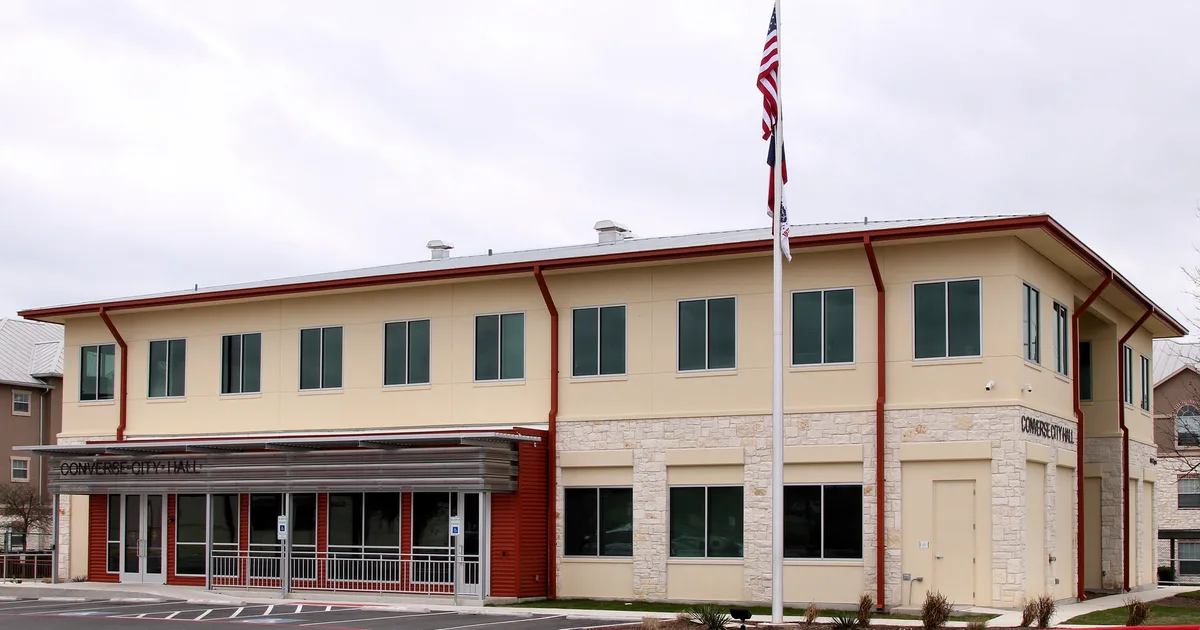
Photo: Larry D. Moore, CC BY 4.0, via Wikimedia Commons (file page). Cropped to 1200×630.
Talk to a broker about Converse
Have a builder's offer? Send it over and we'll put an outside quote next to it from more than 50 wholesale lenders. CapFi Lending is a broker; program terms are set by each lender.