
Mortgage Broker in Seguin
By Dustin Edwards, CapFi Lending
Historic downtown homes, new east-side subdivisions and country acreage: Seguin loans compared across more than 50 wholesale lenders.
Call or text, Mon–Sat 9–7.
Seguin mortgages at a glance
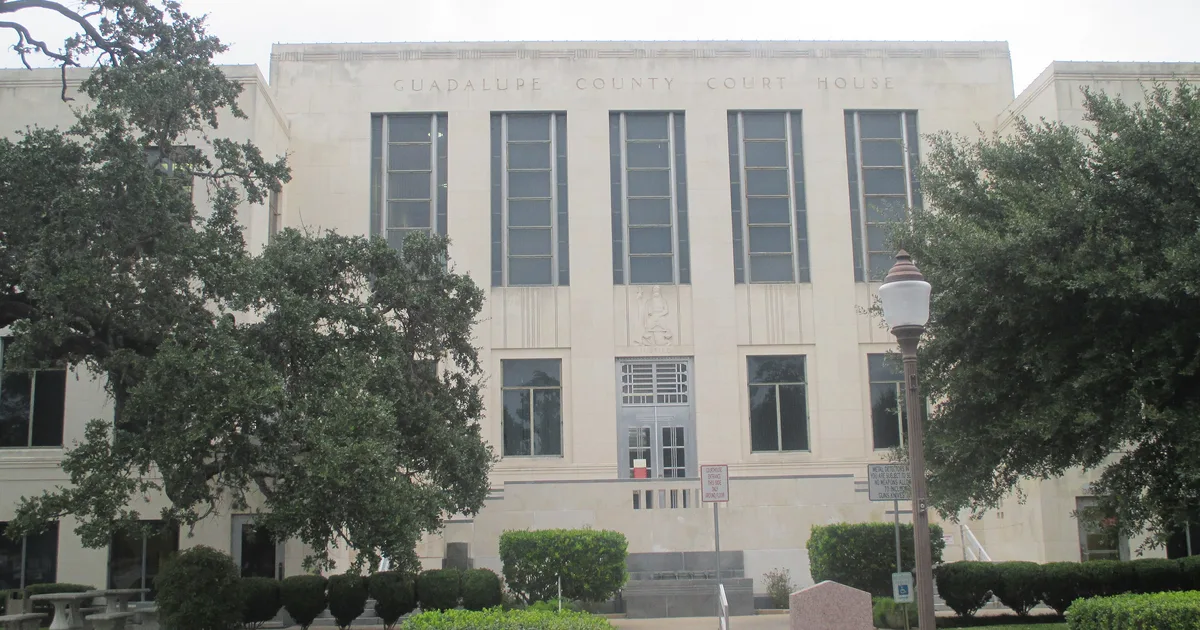
Seguin is the county seat of Guadalupe County, and the courthouse square still anchors the town. Around it you’ll find older frame and brick homes on tree-lined streets, newer subdivisions on the edges of town, and farm-and-ranch property a short drive out. That spread of housing is what makes Seguin different from its suburban neighbors to the west. A single week of calls can include a first-time buyer looking at a 1950s bungalow, a family building on the east side, and a retiree eyeing land along a county road.
- County seat. Seguin is the seat of Guadalupe County, per the county.
- Fast recent growth. 29,433 residents at the 2020 Census and an estimated 41,048 by July 1, 2025 (Census Bureau, V2025), a 39.3% increase over the estimates base.
- Mix of owners and renters. An owner-occupied housing rate of 65.2% (ACS 2020–2024), lower than the county overall, which means plenty of renters who may be ready to buy.
- School district. Seguin ISD is a school taxing unit on the Comptroller’s Guadalupe directory.
- Commuter location. Seguin sits on I-10 between San Antonio and the SH 130 corridor toward Austin.
Seguin facts and sources
| Fact | Figure | Source |
|---|---|---|
| County | Guadalupe (county seat) | Guadalupe County, “About Guadalupe County” |
| Population, April 1, 2010 | 25,175 | U.S. Census Bureau QuickFacts |
| Population, April 1, 2020 | 29,433 | U.S. Census Bureau QuickFacts |
| Population estimate, July 1, 2025 | 41,048 | U.S. Census Bureau QuickFacts (V2025) |
| Owner-occupied housing rate | 65.2% | U.S. Census Bureau QuickFacts, ACS 2020–2024 |
| Median value of owner-occupied homes | $249,400 | U.S. Census Bureau QuickFacts, ACS 2020–2024 |
| Median gross rent | $1,187 | U.S. Census Bureau QuickFacts, ACS 2020–2024 |
| Land area | 38.28 sq. mi. (2020) | U.S. Census Bureau QuickFacts |
| City and school taxing units | City of Seguin; Seguin ISD | Texas Comptroller, Guadalupe County directory |
The city’s land area grew from 34.46 square miles in 2010 to 38.28 in 2020, according to the Census Bureau, and its population estimate has climbed sharply since. That combination, more land inside the city plus new rooftops, is the backdrop for the new subdivisions buyers see on the edges of town.
Three kinds of Seguin purchases, three different loan conversations
The in-town older home. Close to the courthouse square, many homes were built decades ago. They tend to have character and mature trees, and they also come with original windows, older electrical panels, pier-and-beam foundations or additions done by previous owners. None of that rules out financing, but it does shape it. An FHA or VA appraiser will note health and safety items, and a conventional lender will want the home to be livable as-is. The time to learn what a house needs is during your option period, not the week before closing. If the seller won’t make repairs, we can talk about whether a different program or a price adjustment makes more sense.
The newer subdivision. On the edges of town, newer neighborhoods bring builder contracts, HOA dues and sometimes a special district tax. Builders often advertise incentives tied to their own lender. Those can be worth having, but compare the full picture: the incentive, the loan terms and what you pay at closing. We’re glad to put an outside quote next to the builder’s so you can see the difference in writing.
The rural tract. Outside city limits, property questions take over. Is there a well, and has the water been tested? Is the septic system permitted and working? How many acres, and are there outbuildings or a shop? Is there legal access from a public road? Lenders and appraisers treat these features differently, and some programs cap acreage or exclude income-producing land. That’s a big reason to work with a broker for a country property: one lender’s “no” can be another lender’s routine file.
Loan programs that fit Seguin
Seguin’s housing range is wide, so the program conversation is too. A buyer coming out of a rental often starts with FHA or a first-time buyer option. A veteran coming from Randolph often starts with VA. A rancher or small-business owner may need a lender that accepts nontraditional income. We start with your goals and your paperwork, then look across the lender list.
Non-QM loans
- Bank statement loans let self-employed Seguin buyers, from welders to restaurant owners, qualify on 12 or 24 months of deposits.
- P&L loans use a CPA- or preparer-signed profit-and-loss statement.
- DSCR loans qualify a rental on its rent, useful for investors buying older homes near downtown to rent out.
- Asset depletion counts eligible savings as income for retirees.
- ITIN mortgages serve taxpayers who file with an ITIN.
- After bankruptcy or foreclosure options exist with some lenders; waiting periods vary by lender and chapter.
Terms vary by lender. See all non-QM loan options.
Agency: conventional, FHA, VA
- FHA loans are a common starting point for Seguin’s first-time buyers because they allow smaller down payments and more flexible credit than many conventional loans. FHA appraisals also look at the home’s condition, which matters on older houses.
- Conventional loans fit buyers with steady documented income and solid credit.
- VA loans work for eligible veterans and service members, including those stationed at JBSA who prefer Seguin’s price range and pace.
- First-time buyers should also read our first-time home buyer guide.
USDA on the fringe
USDA guaranteed loans are tied to location and household income. Parts of the Seguin area outside the core may qualify, but eligibility is decided by the USDA’s address-level map, not by a ZIP code or a neighbor’s experience. We check the exact property on eligibility.sc.egov.usda.gov before you plan around it.
Property taxes and your payment
Who sets the value. The Guadalupe Appraisal District appraises Seguin property.
What’s on the bill. A home inside city limits usually carries Guadalupe County, the City of Seguin and a school district such as Seguin ISD, plus any special district. Homes outside city limits skip the city line but may sit in a water or emergency services district. The City of Seguin publishes its adopted rate each year.
Homestead exemption. Apply with the appraisal district once the home is your principal residence (Texas Tax Code §11.13). School districts must exempt $140,000 of value, and another $60,000 if you’re 65 or older or disabled.
The 10% cap. Tax Code §23.23 limits a homestead’s appraised value increase to 10% a year, plus new improvements, starting the year after you qualify.
Protests. Under §41.44, file by May 15 or 30 days after your notice is delivered, whichever is later.
Why it matters. Older Seguin homes bought from long-time owners may have had capped values and exemptions. Once you buy, the cap resets for you, so your tax bill can differ a lot from the seller’s. We estimate taxes from the appraised value, not last year’s bill.
Lakefront homes near Seguin
The Guadalupe River is dammed into a chain of small lakes between New Braunfels and Seguin. GBRA names Lake Dunlap, Lake McQueeney and Lake Placid as part of its Guadalupe Valley hydroelectric system, built between 1928 and 1932. Much of the lakefront housing sits outside city limits. McQueeney, for example, is an unincorporated Census-designated place, not part of the City of Seguin. Before you assume an address is in the city, check the appraisal record for its taxing units.
Lake levels. The lakes went through years of low water after spillgate failures, including Lake Wood’s on March 10, 2016 and Lake Dunlap’s on May 14, 2019 (GBRA, May 2019). GBRA reports new spillgates at all three lakes. Lake Dunlap was restored in October 2023. Lake Placid began refilling on February 17, 2026 and reached normal pool on April 20; Lake McQueeney began on March 17 and reached normal pool on April 21 (Guadalupe Valley Lakes). Meadow Lake remains out of hydroelectric service. Check GBRA for current conditions before you make an offer.
Flood zones and insurance. Look up the address on FEMA’s Flood Map Service Center. If the home is in a Special Flood Hazard Area, lenders on federally backed loans require flood insurance. An elevation certificate can help you get an insurance quote, so ask the seller for one early.
Appraisals. Waterfront homes can have fewer close comparable sales, so ask your appraiser how the property compares with other recent waterfront sales.
How you’ll use it. Second-home financing has its own occupancy rules. A home you plan to rent out is a different loan, often a DSCR loan. Above the 2026 conforming limit of $832,750 (FHFA), a jumbo loan or non-QM option may fit.
How buying in Seguin works
- Pre-approval. We review your income and credit and compare FHA, VA, conventional, USDA and non-QM options side by side.
- Choose the area. Historic neighborhoods, newer subdivisions and rural tracts each bring their own questions: age of the home, HOA or MUD, well and septic.
- Offer. Your agent writes the offer with an option period. On older homes, use that window for a thorough inspection.
- Appraisal. Older homes can bring up repair items for FHA or VA appraisals, such as peeling paint, roofing or electrical issues. We tell you ahead of time what an appraiser is likely to flag so the seller can address it.
- Close. Title, survey, final underwriting and signing, usually at a local title office.
What makes CapFi different
We’re a mortgage broker with access to more than 50 wholesale lenders, so a Seguin buyer isn’t limited to one bank’s guidelines. CapFi Lending was founded in 2017, and I’ve been in the loan business since 2004, 22 years as of 2026. Seguin files often need a lender comfortable with older homes, rural features or self-employment income. Knowing which lenders are comfortable with each is most of the job.
We’re based in Austin and licensed throughout Texas. Applications, disclosures and most signatures happen online, and you can call or text us six days a week.
Seguin mortgage FAQs
Is Seguin eligible for USDA loans?
Some properties in the Seguin area may be, especially outside the city’s core, but USDA decides eligibility address by address and also applies household income limits. We check the specific property on USDA’s eligibility map before you rely on it.
What school district serves Seguin?
Seguin ISD serves much of the city and surrounding area and is listed as a school taxing unit on the Comptroller’s Guadalupe County directory. Some addresses near the edges may fall into a neighboring district such as Navarro ISD or Marion ISD, so confirm with the district and the tax record.
How do older homes in historic Seguin affect appraisal?
The appraiser values the home on comparable sales and notes its condition. FHA and VA appraisals also check minimum property standards, so items like failing paint on a pre-1978 home, roof damage or unsafe wiring may need to be fixed before closing. A good inspection during your option period helps you plan.
Can I commute to Austin or San Antonio from Seguin?
Many residents do. Seguin sits on I-10, with San Antonio to the west and the SH 130 toll road reaching north toward Austin. Drive times vary by traffic and where you work, so test the commute at rush hour before you buy.
What are property taxes like in Seguin?
They depend on the taxing units on your parcel: Guadalupe County, the City of Seguin if you’re inside city limits, your school district and any special district. Rates change yearly. We pull the current appraisal record and adopted rates for the address when we build your payment estimate.
Can I buy a house in Seguin that needs work?
Often, yes. Depending on the home and the lender, options can include a standard loan after the seller makes repairs or a renovation-friendly program. We’ll talk through what the appraisal is likely to require.
Do I need flood insurance for a lakefront home near Seguin?
It depends on the flood zone. If FEMA maps the home in a Special Flood Hazard Area, your lender will require flood insurance. We check the FEMA map and ask for any elevation certificate before you’re under contract. Insurance can still make sense outside the mapped zone.
Nearby areas
Sources (checked Nov 5, 2026)
- Guadalupe County, “About Guadalupe County” (seat in Seguin): https://www.guadalupetx.gov/page/about.guadalupe_co
- U.S. Census Bureau QuickFacts, Seguin city, Texas (2010/2020 Census; V2025; ACS 2020–2024; land area): https://www.census.gov/quickfacts/fact/table/seguincitytexas/PST045225
- Texas Comptroller, Guadalupe County directory (City of Seguin; Seguin, Navarro, Marion ISDs): https://comptroller.texas.gov/taxes/property-tax/county-directory/guadalupe.php
- Guadalupe Appraisal District: https://www.guadalupead.org/
- City of Seguin: https://www.seguintexas.gov/
- USDA property eligibility map: https://eligibility.sc.egov.usda.gov/
- GBRA, Hydrolakes (Dunlap, McQueeney, Placid; spillgate completion and normal-pool dates; Meadow Lake status): https://www.gbra.org/operations/hydrolakes/
- Guadalupe Valley Lakes (refill start and normal-pool dates, Placid Apr 20 / McQueeney Apr 21, 2026): https://gvlakes.com/
- GBRA news release, May 2019 (Lake Wood failure Mar 10, 2016; Dunlap May 14, 2019): https://www.gbra.org/news/2019/05/gbra-to-expand-restricted-zones-near-dams-on-lake-mcqueeney-lake-placid/
- FHFA 2026 conforming loan limits ($832,750): https://www.fhfa.gov/news/news-release/fhfa-announces-conforming-loan-limit-values-for-2026
- FEMA Flood Map Service Center: https://msc.fema.gov/portal/home
- U.S. Census Bureau, 2020 Gazetteer, Texas places (McQueeney CDP): https://www2.census.gov/geo/docs/maps-data/data/gazetteer/2020_Gazetteer/2020_gaz_place_48.txt
- Texas Tax Code §§11.13, 23.23, 41.44: https://statutes.capitol.texas.gov/
Photo: Billy Hathorn, CC BY 3.0, via Wikimedia Commons (file page). Cropped to 1200×630.
Talk to a broker about Seguin
From a courthouse-square bungalow to a few acres off a county road, we'll compare your Seguin loan across more than 50 wholesale lenders. CapFi Lending is a broker; program terms are set by each lender.